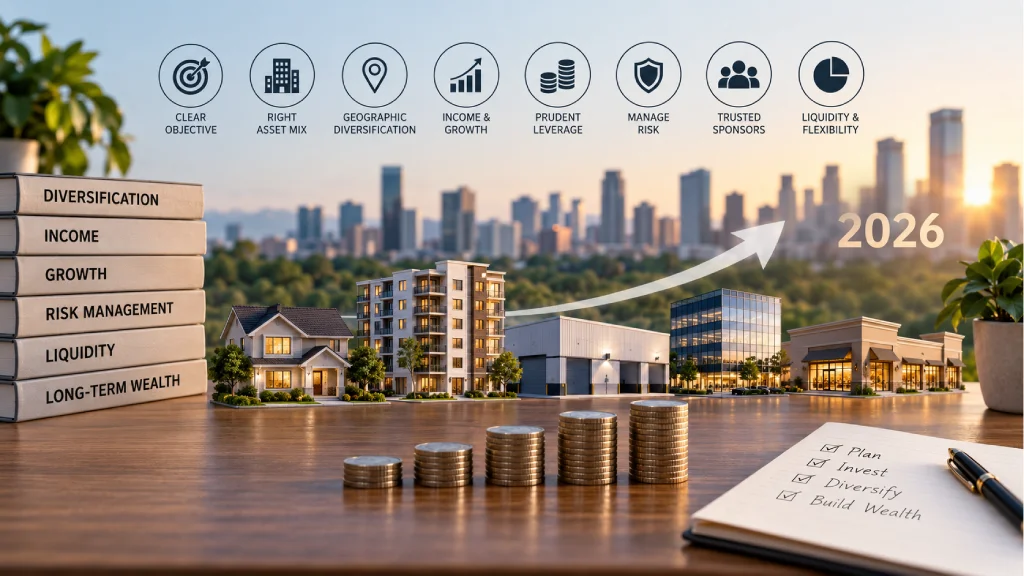
A strong real estate investment portfolio is not simply a collection of properties.
It is a group of investments that work together around a clear objective, with risks you understand, sufficient liquidity, an appropriate amount of leverage, and a strategy that does not depend on every assumption being correct.
That distinction matters in 2026.
The U.S. real estate market is offering opportunities, but investors are still navigating uncertainty around interest rates, inflation, operating costs, labor, regulation, and property-level fundamentals. PwC and the Urban Land Institute describe 2026 as a market requiring investors to navigate significant uncertainty, while CBRE expects U.S. commercial real estate investment activity to increase in 2026 and emphasizes asset selection and management as important drivers of returns.
For an investor, the question is therefore not simply, “What should I buy?”
A better question is:
“What should my overall portfolio look like so that each investment has a clear purpose and the portfolio remains resilient when conditions change?”
Here are the major elements to consider.
Start With a Clear Portfolio Objective
Before choosing individual investments, determine what you want your real estate portfolio to accomplish.
Your objective might be to:
- Generate current income
- Build long-term wealth
- Preserve capital
- Diversify an existing investment portfolio
- Create passive income
- Gain exposure to income-producing real estate
- Balance growth-oriented investments with more stable assets
These objectives can lead to very different portfolios.
An investor who needs current income may evaluate stabilized, income-producing properties differently from an investor who is comfortable committing capital for a longer period in pursuit of potential appreciation.
There is no universal portfolio formula.
The appropriate structure depends on your financial objectives, investment horizon, liquidity needs, risk tolerance, tax circumstances, and the role real estate plays within your broader financial plan.
The first step is knowing what the portfolio is supposed to accomplish.
Diversify Beyond the Number of Properties
Owning more properties does not automatically mean having a diversified real estate investment portfolio.
Consider an investor who owns six properties but all six are concentrated in the same metropolitan area and depend on similar tenants. A local economic downturn, rising operating costs, regulatory changes, or weaker demand could affect much of the portfolio at the same time.
Diversification should therefore be viewed across several dimensions:
- Asset type: multifamily, industrial, self-storage, retail, office, healthcare, hospitality, land, or other real estate.
- Geography: different markets may have different employment bases, population trends, supply conditions, regulations, and economic drivers.
- Strategy: investments may have different objectives, such as income generation, value creation, redevelopment, or long-term appreciation.
- Sponsor or operator: passive investors should consider how much of their capital depends on one investment manager or operating partner.
The goal is not to own everything.
The goal is to avoid concentration that you have not consciously chosen.
Choose Asset Types for Their Fundamentals, Not Their Popularity
Different property types respond to different economic forces.
Multifamily properties may be influenced by household formation, employment, rent growth, new supply, occupancy, and operating expenses.
Industrial assets can be affected by logistics, manufacturing, distribution, tenant demand, location, and broader economic activity.
Self-storage has a different demand profile again, while NNN properties may place greater emphasis on tenant quality, lease structure, location, and contractual income.
There is no single “best” asset class for every investor.
The important question is whether an asset’s characteristics fit your portfolio objectives.
For example, adding an investment simply because a sector is popular in 2026 is not diversification by itself. The investment still needs to make sense based on valuation, operating fundamentals, debt, demand, business plan, and risk.
Current industry research also shows why selective decision-making matters. PwC and ULI identify data centers and senior housing among the sectors attracting significant attention in 2026, while also highlighting a more divided outlook across property types.
A strong portfolio is built on fundamentals, not headlines.
Review Geographic Concentration
Property count can hide geographic concentration.
Five investments in five different buildings within the same market can still be exposed to many of the same risks.
Ask:
- What percentage of my portfolio is tied to one market?
- Are my investments dependent on the same local employers?
- Are they exposed to the same property taxes and regulations?
- Are they affected by similar insurance conditions?
- Is new supply increasing in the markets where I invest?
- Do the markets have different economic drivers?
Geographic diversification can reduce the impact of a problem concentrated in one market.
But more cities are not automatically better.
An unfamiliar market can create its own risks if an investor does not understand the local economy, supply pipeline, demographics, tenant demand, or operating environment.
Diversify deliberately rather than geographically for its own sake.
Balance Current Income With Long-Term Growth
A strong real estate investment portfolio may contain investments with different return drivers.
Some investments may emphasize current cash flow. Others may require operational improvements, leasing, renovations, development, or market growth before their full potential is realized.
Understanding that difference is important.
Suppose every investment in a portfolio depends heavily on future appreciation or a successful execution of a complex business plan. The portfolio may be more aggressive than its number of properties suggests.
Conversely, focusing only on current distributions can lead investors to overlook asset quality, future capital requirements, debt structure, or long-term value creation.
Look at both sides:
Income today can support portfolio cash flow.
Potential growth may contribute to long-term wealth creation.
Risk determines how dependable those expectations may be.
The right balance depends on the investor and the role each investment is intended to play.
Evaluate Debt at the Portfolio Level
Debt should not be reviewed only one property at a time.
For your overall real estate investment portfolio, understand:
- How much debt you have
- The proportion of fixed-rate versus variable-rate debt
- When major loans mature
- Which investments depend on refinancing
- Whether multiple loans mature during the same period
- How much liquidity is available for unexpected capital needs
- How sensitive portfolio performance is to higher financing costs
This is particularly relevant in 2026 because financing conditions remain a major consideration for real estate investors. PwC’s 2026 outlook identifies interest rates and cost of capital among the industry’s leading concerns. CBRE also expects returns to remain substantially income-driven, making asset selection and management increasingly important.
A property can perform well operationally and still create portfolio stress if its financing becomes difficult to manage.
The debt structure is therefore part of the investment thesis, not merely a financing detail.
Maintain Liquidity Outside Private Real Estate
Private real estate can be illiquid.
That matters because an investor may not be able to sell an investment quickly simply because cash is suddenly needed elsewhere.
A portfolio review should therefore include the capital you have outside real estate.
Consider potential needs such as:
- Personal liquidity
- Business expenses
- Taxes
- Unexpected capital requirements
- Family obligations
- Future investment opportunities
- Emergency reserves
The appropriate liquidity level varies by investor.
The important principle is straightforward: do not commit so much capital to illiquid investments that an unexpected need forces you into a difficult financial decision.
Liquidity is part of portfolio construction.
Consider Sponsor and Operator Concentration
Sponsor concentration can be easy to overlook, particularly for passive investors.
You may own investments across multifamily, industrial, and self-storage and still have significant concentration if the same sponsor or operating team manages most of them.
That creates another layer of exposure.
The sponsor’s underwriting process, communication, financial management, operating capabilities, decision-making, and response to changing conditions can all influence the experience and outcome of a private investment.
That does not mean investing with the same experienced sponsor is necessarily a problem.
It means you should understand how dependent your overall portfolio is on one team.
For passive real estate investors, diversification can therefore involve more than property types and markets. It can also involve the people and organizations responsible for executing the investment strategy.
Know Where the Cash Flow Comes From
A distribution or income payment tells you what was received.
It does not necessarily tell you why it was received.
When reviewing an investment, understand whether cash flow is primarily supported by property operations, changes in occupancy, rental income, asset sales, reserves, additional financing, or other sources.
Questions worth asking include:
- Is the property generating the expected operating income?
- Is occupancy improving or declining?
- Are rents supporting the business plan?
- Are expenses increasing faster than revenue?
- Are reserves being used?
- Is additional capital likely to be required?
Understanding the source of cash flow gives investors a clearer picture than simply looking at the amount deposited into an account.
Intentionally Mix Risk Levels
Every investment does not need the same risk profile.
A portfolio could contain relatively stabilized investments alongside opportunities that involve more renovation, leasing, development, operational improvement, or other execution requirements.
What matters is knowing where those risks sit.
For every investment, identify whether the outcome depends heavily on:
- Appreciation
- Rent growth
- Occupancy improvement
- Renovation execution
- Development timelines
- Refinancing
- Lease-up
- Cost control
- A particular exit valuation
Then look at the combined portfolio.
If nearly every investment requires several favorable assumptions to succeed, the portfolio may be more aggressive than it appears.
Diversification should reduce unwanted concentration, not simply increase the number of investment statements you receive.
Include Real Estate Exposure That Fits Your Overall Portfolio
Real estate does not have to mean only direct property ownership or private investments.
Publicly traded REITs can provide exposure to income-producing real estate through securities that trade on public exchanges. The SEC notes that publicly traded REITs are typically more liquid than non-traded REITs, but investors should still understand that REITs carry their own risks and can specialize in very different property sectors.
For some investors, publicly traded real estate may complement private investments.
For others, private real estate opportunities may better fit their goals, risk tolerance, time horizon, and eligibility.
The important point is to consider real estate exposure as part of the investor’s overall portfolio, rather than evaluating every investment in isolation.
Build a Portfolio You Can Actually Understand
Sophisticated investing does not necessarily mean owning dozens of different investments.
A portfolio can become unnecessarily complicated when an investor cannot explain what each investment is doing.
For every holding, you should be able to answer:
- What role does this investment play?
- What is the primary source of its expected return?
- What are the main risks?
- How much capital is committed?
- When might additional capital be required?
- How liquid is the investment?
- What assumptions need to be correct for the investment thesis to work?
If you cannot answer those questions, the problem may not be that you need another investment.
You may need a better understanding of the investments you already own.
What Should a Real Estate Investment Portfolio Include in 2026?
There is no universal percentage allocation that makes a portfolio “correct.”
Instead, evaluate your portfolio across several layers:
| Portfolio Layer | What to Evaluate |
|---|---|
| Objectives | Income, growth, preservation, diversification, or a combination |
| Asset Type | Multifamily, industrial, self-storage, NNN, and other opportunities |
| Geography | Market concentration and different economic drivers |
| Income | Current cash flow and its underlying source |
| Growth | Appreciation and value-creation assumptions |
| Debt | Leverage, interest-rate exposure, and loan maturities |
| Liquidity | Capital available outside illiquid investments |
| Sponsors | Dependence on individual operators or investment groups |
| Risk | Execution, market, financing, leasing, and operational risks |
| Oversight | How frequently the portfolio is reviewed |
This framework is more useful than asking how many properties you should own.
Review the Portfolio Regularly
A real estate investment portfolio should evolve as circumstances change.
Markets change.
Property performance changes.
Debt matures.
Operating costs change.
Your financial objectives can change as well.
At regular intervals, review:
- Asset and geographic concentration
- Debt exposure and maturity dates
- Current income
- Capital requirements
- Sponsor concentration
- Portfolio liquidity
- Changes in investment assumptions
- Investments that no longer fit your objectives
A portfolio that made sense five years ago may not have the same role today.
Regular review helps investors identify that change before it becomes a larger problem.
How Loomba Approaches Real Estate Investment Opportunities
Loomba Investment Group focuses on private placement opportunities in commercial real estate, with an emphasis on carefully selected, risk-conscious investments and investor education. Its documented strategy includes multifamily, industrial, and NNN real estate, supported by market research, due diligence, risk assessment, transparency, and ongoing investor communication.
The firm’s approach is relevant to the broader portfolio question because evaluating an individual opportunity should be part of evaluating the investor’s overall strategy.
Loomba’s founder and CEO, Vinki Loomba, has an MBA and more than 20 years of experience spanning real estate, finance, and technology. Her investment experience includes multifamily, industrial, self-storage, and land development.
For accredited investors exploring private real estate opportunities, this type of due-diligence-oriented approach can help create a clearer framework for assessing how a potential investment may fit within an existing portfolio.
The Bottom Line
A strong real estate investment portfolio in 2026 is not necessarily the largest portfolio.
It is the portfolio where the investor understands the purpose, risk, liquidity, financing, and expected role of each investment.
Diversification matters, but it should go beyond property count.
Look at asset type, geography, debt, sponsor concentration, cash-flow sources, liquidity, and the assumptions behind each investment.
The most important question may be this:
What happens to the portfolio if one or two assumptions turn out to be wrong?
That question shifts portfolio construction away from simply accumulating properties and toward managing risk thoughtfully.
For accredited investors considering private real estate, the next step is not to chase whichever asset class is receiving the most attention.
It is to evaluate opportunities within the context of your broader financial strategy, conduct appropriate due diligence, and determine whether an investment actually fits your objectives.
That is what turns a collection of real estate investments into a thoughtfully structured portfolio.
Your next chapter does not begin with everything figured out. It begins with awareness and one intentional yes.
Disclaimer
This content is for educational and informational purposes only and does not constitute investment, legal, tax, or financial advice. Real estate investing involves risk, including the potential loss of principal. Outcomes are not guaranteed and depend on market conditions, property performance, and economic factors. Past performance is not indicative of future results. Readers should conduct their own due diligence and consult qualified professionals before making investment decisions.
Newsletter
Sign up our newsletter to get update information, news and free insight.
Latest Post
August 24, 2026
February 3, 2026
January 22, 2026
January 22, 2026